Metro Manila ended 2025 with roughly 79,200 unsold condominium units and a vacancy rate of 24.7 percent. At the midpoint of that year, the unsold stock represented 13.4 years of supply at the prevailing pace of take-up. The Philippines has permitted foreign condominium ownership since 1966, longer than any other market in Southeast Asia, which makes it the most complete case study available to anyone assessing Cambodia condo foreign ownership in 2026.
The comparison is usually made backwards. Manila is cast as the mature market and Phnom Penh as the one still arriving. Read the two frameworks side by side and a different picture forms. Cambodia did not copy the Philippine model. It built its own framework forty-four years later, and built something structurally simpler.
Two instruments with the same name
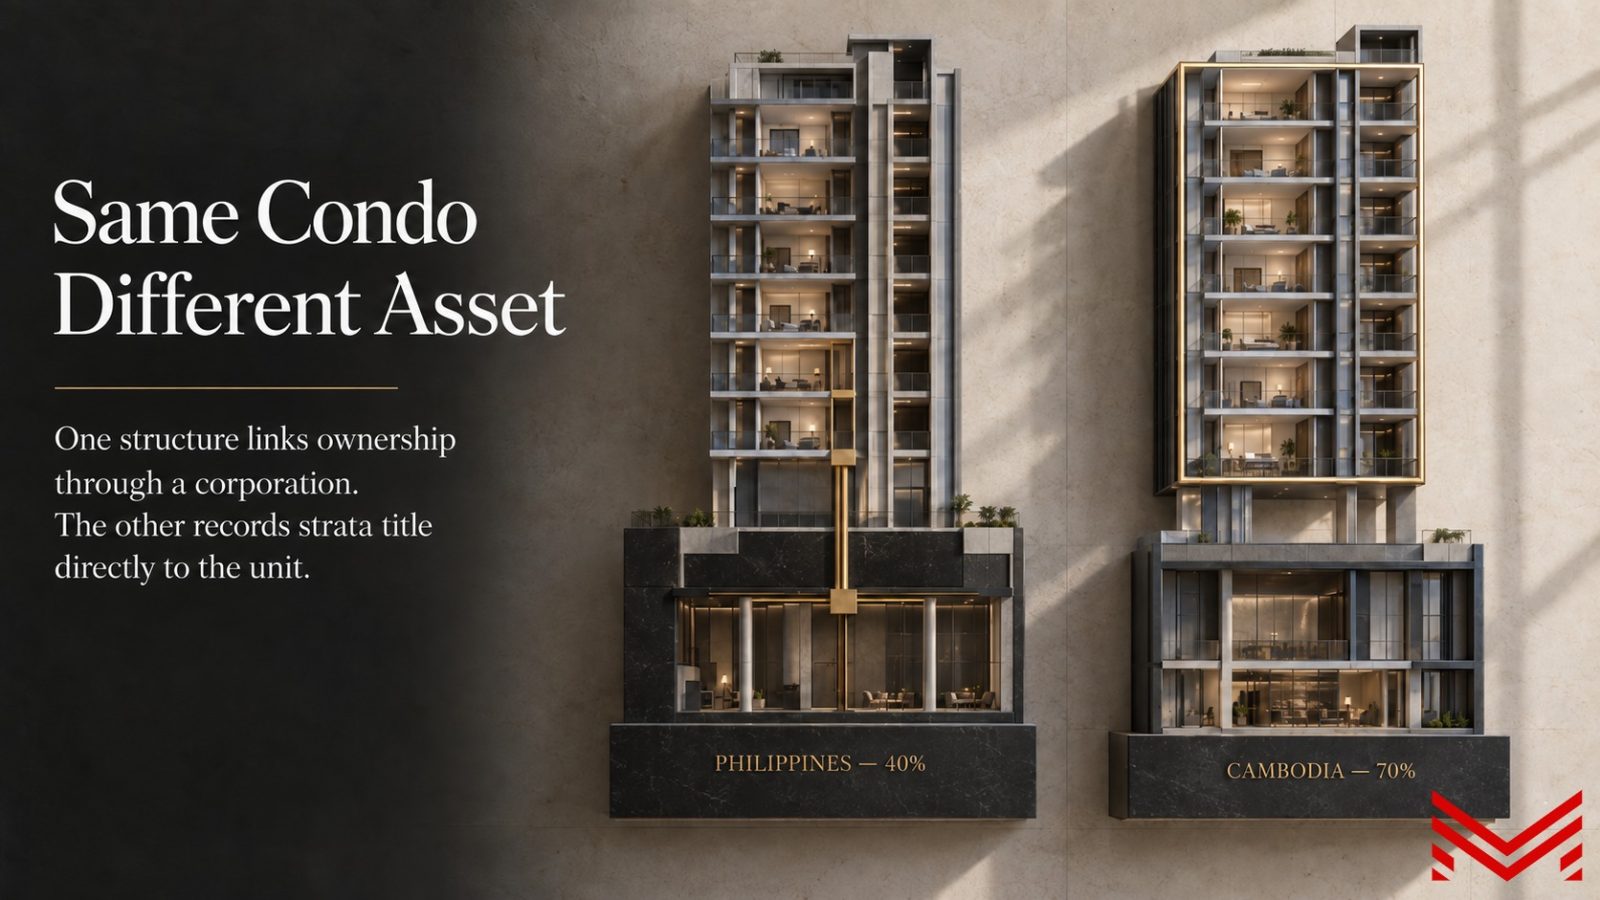
Republic Act 4726, the Philippine Condominium Act of 1966, operates under a constitutional rule reserving land for Filipino citizens and Filipino-majority corporations. The solution was an elegant piece of legal engineering. A condominium corporation holds the land. The buyer owns the unit and a proportionate interest in that corporation. Foreign participation is capped at 40 percent of the project.
A foreign buyer in Manila therefore holds two things at once: a unit, and a minority position in a company that must remain 60 percent Filipino for the life of the building.
Cambodia's 2010 Law on Providing Foreign Ownership Rights in Private Units of Co-Owned Buildings takes a different route to a similar destination. Foreigners may own up to 70 percent of the private units in a co-owned building, excluding the ground floor and below. Ownership is recorded as strata title in the buyer's own name. No intermediate corporation. No membership interest. No domestic majority to maintain across decades of unit turnover.
One system gives a foreigner a share in the company that owns the land. The other gives a foreigner title to the space in the sky. These are not the same asset, and they do not behave the same way at resale.
Where each system places the safety net
The Philippines protects the buyer at the contract level, and it has done so since the 1970s. Presidential Decree 957 requires project registration and a license to sell before a unit can be marketed. Republic Act 6552, the Maceda Law, governs what happens when an installment buyer falters: one month of grace for every year of payments made, never less than 60 days, and after two years of installments a cash surrender value of 50 percent of total payments, rising 5 percent for each year beyond the fifth, capped at 90 percent.
Cambodia places its net at the project funding level. Under the current regulatory framework, a residential development of 30 units or more requires a license from the Real Estate Business and Pawnshop Regulator. Capital thresholds are stated in the rules rather than implied: 100 percent of construction cost for one license class, 20 percent for the other. Developers deposit 2 percent of total construction cost with the regulator or produce a business security guarantee from a licensed Cambodian bank. The 2019 Trust Law added a further layer, allowing buyer funds to sit with a licensed trustee rather than on the developer's balance sheet, and licensed escrow providers have continued to come online through 2026.
Read the two side by side and the design intent separates cleanly. The Philippine system assumes the building will be completed and asks what happens if the buyer stops paying. The Cambodian system asks what happens if the developer stops building. Both are reasonable questions. An off-plan buyer should know which one their jurisdiction answers by statute, and arrange the other one contractually.
What Cambodia condo foreign ownership does not solve
Manila's oversupply accumulated inside one of the region's most developed legal frameworks. Sixty years of condominium law. A dedicated buyer protection statute. Mandatory licensing since 1976. Listed developers with audited accounts and analyst coverage. None of it produced a 24.7 percent vacancy rate, and none of it prevented one either.
The dispersion inside that number is the part worth studying. Bay Area vacancy runs above 50 percent. Makati CBD, Rockwell and Ortigas sit below 15 percent. Same country, same law, same 40 percent cap, outcomes separated by a factor of three.
Legal maturity protects the title. It does not protect the price. That distinction is the single most transferable lesson from Manila to Phnom Penh, and it points every serious question away from the statute book and toward the pipeline: how many units are being delivered within walking distance of yours, on what timeline, at what price point, to which end user.
The exit question
The Philippines spent two decades building liquidity infrastructure around the condominium asset. A functioning peso mortgage market. A listed REIT sector operating since 2020 under Republic Act 9856, which introduced an institutional bid where previously there was only a retail one. Depth of that kind changes the character of an exit.
Cambodia's condominium exit remains primarily buyer to buyer, in US dollars, largely cash. That is not a defect to be corrected in the underwriting. It is a condition to be priced into it. The practical consequence is that a Cambodian holding is underwritten on yield and hold period rather than on resale velocity, and the dollar denomination removes a currency translation risk that the Philippine buyer carries on every peso of rent collected.
The friction costs differ as well. Cambodia's 20 percent capital gains tax on immovable property has been deferred again, most recently to the end of 2026, while transfer tax on hard title stands at 4 percent. A Philippine disposal carries 6 percent capital gains tax plus documentary stamp tax and local transfer charges. Those figures belong in the model at the point of entry, not at the point of sale.
A title is a claim on an asset. Liquidity is a claim on a buyer. The two do not arrive together, and the second one takes far longer to build.
Cambodia's framework is younger than the Philippines' and, on the specific question of what a foreign buyer actually holds, cleaner.
The question worth asking before any off-plan commitment is not whether the law permits foreign ownership. Both markets settled that question decades apart and both answered yes. The question is whether the submarket can absorb what is being built beside you, at the price you were quoted, on the timeline you were promised. That work is unglamorous and it is done before the reservation fee, not after.
At My First Corner, this is the analysis we run before a client signs anything. The conversation is available when it is useful.