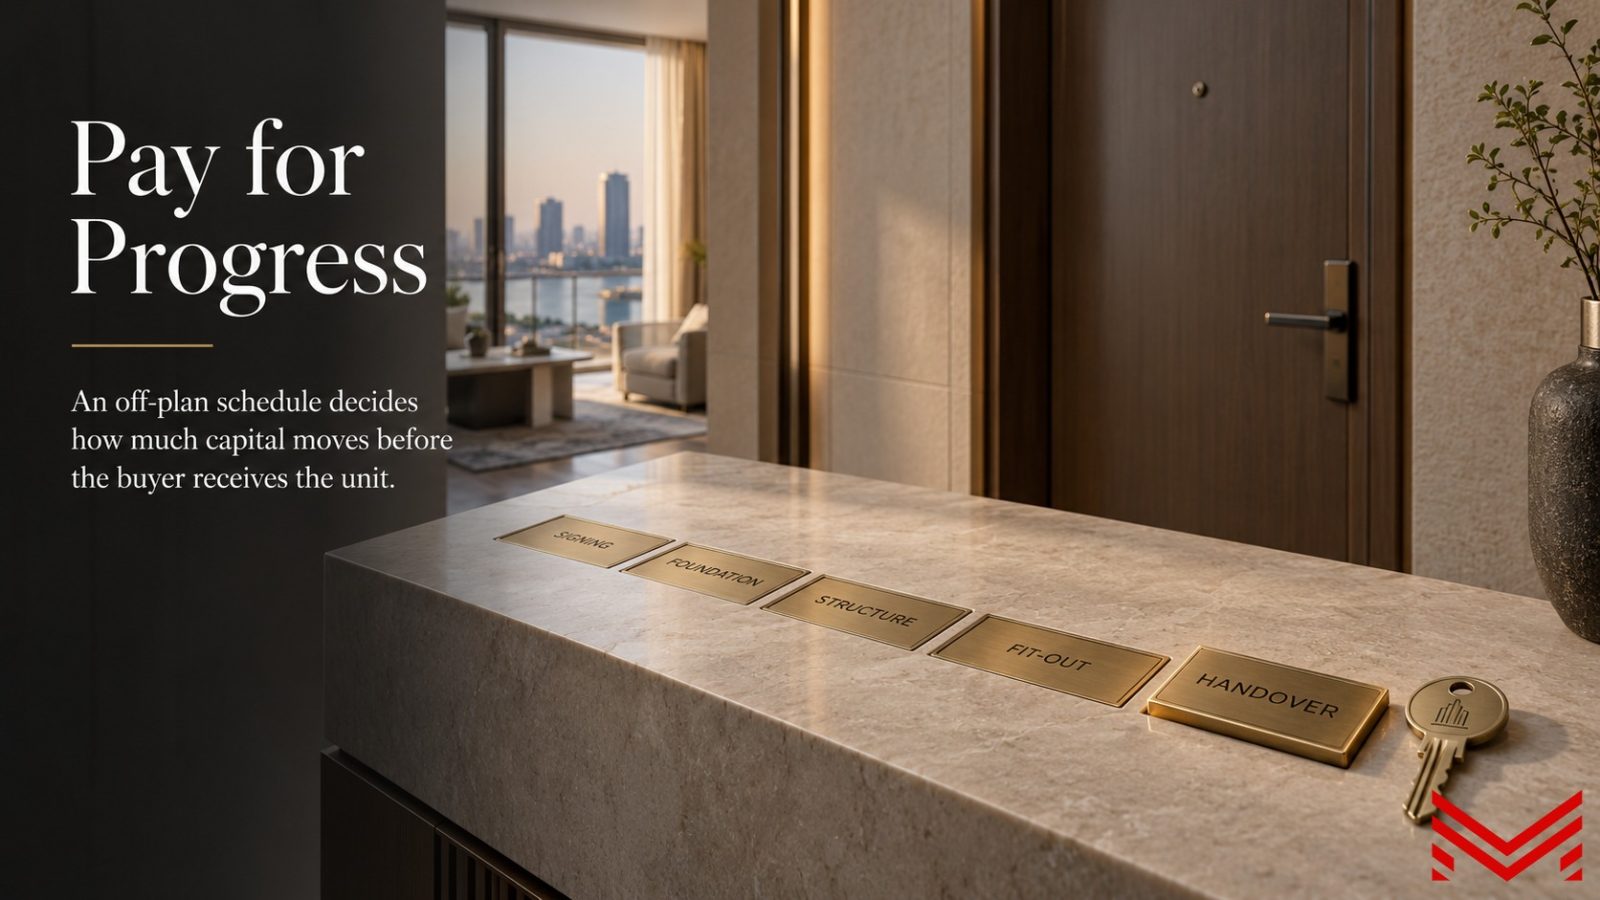
A standard off-plan payment schedule in Phnom Penh moves in five to seven tranches, from a down payment of 20 to 30 percent at signing to a final payment due at handover. Most buyers read that schedule as a budget, a question of how much leaves the account and when. The more useful reading treats it as a risk ledger, because the schedule quietly decides how much of the project's completion risk the buyer agrees to carry, and at what point in the build.
That distinction is the whole subject. A unit that has not been built yet is a promise. The payment schedule is the instrument that sets when the buyer starts paying for the promise rather than the finished thing.
Two ways to write an off-plan payment schedule
Two schedules can look almost identical on the surface and allocate risk in opposite directions. The difference is what each installment is tied to.
A time-based schedule releases payments on a calendar. Twenty percent at signing, then a fixed percentage every three or four months until handover. The installments arrive whether or not the building has risen to match them. A milestone-based schedule ties each payment to a verifiable stage of construction: foundation complete, structure topped out, mechanical and electrical systems installed, internal fit-out finished.
The two produce the same total. They do not produce the same exposure. Under a time-based schedule, a buyer can be 60 percent paid on a project that is 30 percent built. Under a milestone-based schedule, the money and the concrete move together, and a stalled site stops the buyer's outflow at roughly the point the work stopped. When a schedule is written against the calendar rather than the structure, read it twice.
What each tranche is actually buying
The down payment, typically 20 to 30 percent, secures the unit and the price. It is the least exposed money in the schedule, because at that stage the buyer is still purchasing optionality more than exposure.
The construction installments, which usually total 40 to 60 percent across the build, are where the real risk transfer happens. Each one converts the buyer from a holder of a promise into a financier of the work. Every dollar paid in during construction is, in effect, a dollar of the developer's build cost that the buyer has agreed to fund ahead of delivery. That is not a criticism of the model. Pre-sales are how mid-market developments get capitalized, and the discount to completed pricing is the buyer's compensation for supplying that capital early. The point is only to see the trade for what it is. The buyer is being paid, in price, to take construction-stage risk, and the schedule sets the size of the position.
The handover tranche is the buyer's position of strength
The final payment, anywhere from 10 to 40 percent, is the most important number in the schedule and the one buyers most often try to shrink for cash-flow reasons. Shrinking it can be a mistake.
The handover tranche is the buyer's remaining leverage. It is the money the developer has not yet received, and therefore the money that keeps the developer attentive through snagging, title issuance, and the gap between a building that is called finished and one that actually is. A schedule that leaves 10 percent at handover hands the developer nearly all of its cash before the buyer has inspected a single completed surface. A schedule that holds back 30 percent or more keeps both parties' interests aligned through the one stage where alignment matters most. Consider two units at the same price. One asks for 90 percent before keys, the other for 70 percent. The second buyer is holding three times the corrective power at the exact moment defects surface. In a first transaction, a larger back-end is usually the buyer's friend, whatever it does to the deposit math.
Where the money sits between payment and completion
A tranche paid is not the same as a tranche protected. The second question, after when the buyer pays, is where the payment goes once it has been made.
Funds paid directly into a developer's operating account fund construction and, in a difficult scenario, sit inside the developer's balance sheet alongside every other claim on it. Funds held in a dedicated project or stakeholder account, released against verified progress, sit one step further from that risk. The mechanism matters more than the language around it. A buyer weighing two projects at similar prices and similar yields should treat the payment-handling structure as a real line item in the comparison, not a formality to be skimmed at signing.
Reading the schedule before signing it
The schedule reveals a deal's risk posture more honestly than the brochure does, and a handful of questions surface most of it. Is each installment tied to a construction milestone or to a date. What percentage falls due before the structure is topped out. How large is the handover tranche, and what has to be true, title included, before it releases. Where do funds sit between payment and completion. What the contract says happens to paid installments if the project runs past a stated delay window.
None of these questions requires legal training to ask. All of them change the answer to the only question that finally matters, which is how much the buyer is exposed, and for how long, before holding a completed and titled unit.
An off-plan payment schedule is not a financing convenience attached to a purchase. It is the purchase's risk structure written in numbers, and it is negotiable more often than buyers assume.
The investor who reads the schedule as a risk ledger rather than a budget tends to ask for milestone triggers, a meaningful handover tranche, and clarity on where money sits, before price is even discussed. That work is unglamorous, and it is where the downside is actually managed.
At My First Corner, the payment schedule is one of the first documents we read on a client's behalf, well before the show unit. The conversation is available when it is useful.